Know what you can borrow.Before your firstviewing.
Enter your income and see what's possible right away.
Everyone has their own story.What's yours?
Whether you're buying your first home, upsizing, or improving your mortgage. It starts with the right conversation.
Different situation? Get in touch, I'm happy to think along.
It can be this simple.
You know exactly what you can borrow. Your monthly payments are clear. And from 45+ lenders, the option that fits your situation has been selected. By an independent mortgage advisor who takes the time. That same week.
You find a home. With every offer, you have a financial statement ready. Someone with property expertise assesses the house with you, advises on your offer, and is beside you at the notary.
No call center. No transfers. One dedicated point of contact, from first consultation to key handover.
One person. From start to keys.
One number for everything.
You know exactly where you stand
How much can you borrow? What will your payments be? What's smart and what isn't? Honest answers. No sales pitch. 45+ lenders compared.
Someone who searches with you
You don't have to do it alone. Viewings. Market analysis. Whether the home is worth its price. Someone with property expertise next to you.
You bid with confidence, not crossed fingers
With every offer: a financial statement. The seller's agent sees your income has been calculated. That makes the difference when there are multiple bidders.
Everything's handled when you get the keys
The bank application. The deed check. Contact with the notary. You don't need to repeat your story. One person handles everything. You sign.
From first click to keys.
Three steps. One point of contact.
I listen and calculate
It starts with a conversation. We talk about your plans first. What do you dream of? What's realistic? I compare 45+ lenders and explain everything in language you understand. Online with no travel, or at your home on request. Always personal contact.
I search and bid with you
If you want, I search with you. Viewings, market analysis, advice on what a home is worth. And when you bid: a statement that shows the seller you're serious. Your bid is backed by the numbers before you make it.
I handle everything until the keys
The bank application. The deed check. Contact with the notary. You sign. And if three months later you have a question, you call the same number.
Curious what you can borrow?
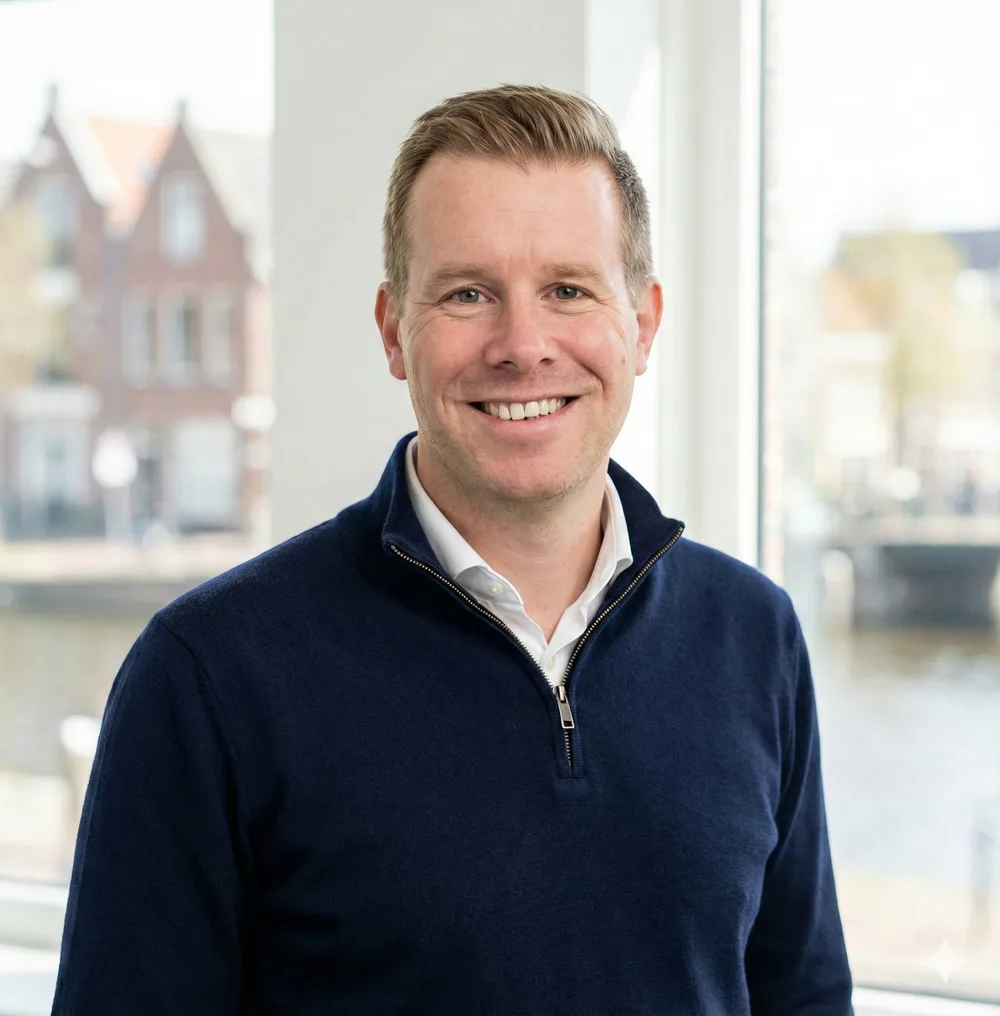
No call center. Just Wouter.
500+
mortgages guided
17
years in the mortgage industry
45+
lenders compared
1
dedicated point of contact
The first stories are on their way.
I am asking the clients I guided over the past years to write down their experience. As soon as they come in, you will read them here in their own words, with name and situation. A handful of real stories beats a page full of polished words.
- 500+ mortgages guided
- 45+ lenders compared
- 17 years of experience
Want to share your experience? After completion you'll receive an invitation.
Good question.
That depends on your income, fixed expenses and the energy label of the property. The calculator at the top of this page gives you an indication in 10 seconds based on the current NIBUD standards for 2026. For an exact calculation, book a free orientation call.
The 30-minute intro call is free and without obligation. If you go ahead with advice, that runs through Hypotheek & more, which is registered with the AFM (the Dutch financial regulator), and I charge their rate. As of September 2026: a first home €2,600, a next home €3,100, refinancing with a different lender €3,100, and staying with your current lender while only changing the terms €950. If you are self-employed and lenders assess your annual accounts, add €500: €3,100 for a first home, €3,600 for a next one. So the advice fee is fixed before we start. If your lender charges a handling fee for the application, add €350. The full rate list and the comparison card are at the bottom of this page, on the Hypotheek & more website.
Yes. Most lenders require at least one year of financial statements, some two or three. Every bank calculates differently. I know which lenders are most flexible with variable income and which fit your business structure. In 17 years I've helped hundreds of entrepreneurs.
You can borrow up to 100% of the property value. The additional costs (notary, appraisal, advice) you pay yourself. First-time buyers aged 18 to 34 (property up to €555,000) pay 0% transfer tax and can expect about 2% in additional costs. Other buyers pay 2% transfer tax and should budget about 4% of the purchase price.
NHG stands for Nationale Hypotheek Garantie (National Mortgage Guarantee). In 2026 the limit is €470,000 (€498,200 with energy-saving measures). The one-time premium is 0.4% of the mortgage amount. If your mortgage is below the limit, you pay a lower interest rate and you're protected in case of forced sale. The premium often pays for itself within two years through lower interest.
A bank advisor only compares products from their own bank. I compare 45+ lenders and advise what fits your situation best. That can mean thousands of euros difference over the term. On top of that, I also help with searching, assessing properties and bidding. You won't get that at a bank.
Yes. With a temporary contract, annual contract or letter of intent from your employer there are options. Some lenders even accept a probation period. It all depends on your specific situation.
You get an indication instantly via the calculator. The full advisory process takes 2 to 4 weeks on average. After that the bank needs another 4 to 6 weeks for the final offer. Already made an offer on a house? We get started the same day.
Yes. I've been working with Mariusz from MOJKA Finance for over 9 years. Together we've helped 50+ Polish families. The entire process can be in Polish or English. Everything is explained, even if the Dutch system is completely new to you.
A financial statement (financieringsverklaring) is a document stating up to which amount I have calculated your income. It is an indication and not a commitment from a lender. Sellers and agents take bids with a statement more seriously. With me you get one as standard with every bid. No extra charge. It's part of my service.
Each lender decides for itself how it treats the 30% ruling, and the policies differ. Lenders calculate with your gross salary; the ruling lowers your tax, and that by itself does not add borrowing capacity. It does leave you more net income each month, which matters for what you can comfortably pay. I check the policy of the lender that fits you and show you both numbers before you commit to anything.
It is common among expats and it rarely stops an application. Dutch lenders check the BKR register, and an empty record simply means there is nothing negative to find. Several lenders are comfortable with international profiles when the file is built properly, with your employment contract, your residence status and your savings shown clearly.
Most lenders do not accept foreign income, even when it is paid in euros. They want you to live and earn in the Netherlands. A few accept it under conditions, with heavier paperwork. A mix of employment and freelance income inside the Netherlands is a different matter: that is common and usually workable with the right documentation. Tell me your situation before you invest time anywhere. I will say honestly whether it fits and where it could work. I have guided files like this for 17 years.
One conversation. That's all it takes.
It is free: 30 minutes where I listen to your situation and tell you what's possible. After that, you decide.
No catch. Just a good conversation.
Prefer to call first? +31 6 22 13 14 29Free orientation call · 30 minutes · No obligations
Mortgage advice is provided through Hypotheek & more, an AFM-registered financial service provider.