Are you paying too much? Let's calculate.
Your mortgage is running. Rates have dropped. Or you see neighbours with lower payments and the same home. Is refinancing smart? Or does the penalty make it more expensive?
“Someone who shows you what switching earns you when it pays off, and why staying put is sometimes the smarter move in your case. An honest answer either way.”
I calculate it honestly. Even when the answer is no.
From doubt to a lower monthly payment.
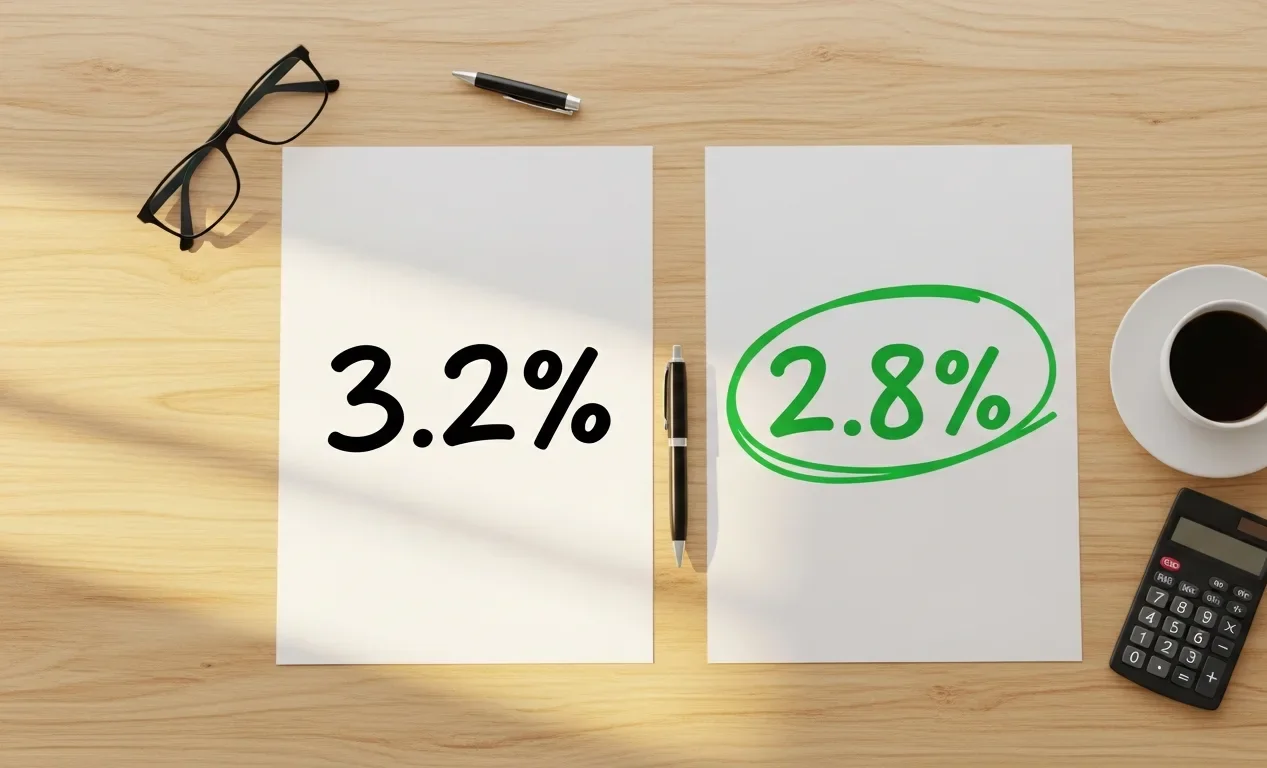
Working through your current position
What are you paying now? What would you pay at a different rate? I compare your current mortgage against the live offering of 45+ lenders.
Costs against savings
Penalty interest, notary, valuation: every cost listed. Set against the saving over the remaining term. An honest picture, in black and white.
The switch arranged
If refinancing pays off, I arrange everything. New offer, valuation, notary. You sign. And from next month you pay less.
An honest comparison
Your current rate beside the live offering. Old and new, in black and white.
Penalty interest calculated
What does leaving your current bank cost? And does the saving outweigh it?
45+ lenders
Tied to no single bank. The lowest rate across the whole market.
Honest advice
If refinancing does not pay off, I say so. No pressure, no hidden interest.
Everything arranged
New offer, valuation, notary. One point of contact for the whole process.
Personal guidance
No call center. No comparison site that stops at "complex". One person, from start to finish.
Curious what you can borrow?
500+
mortgages guided
17
years in the mortgage industry
45+
lenders compared
1
dedicated point of contact
The first stories are on their way.
I am asking the clients I guided over the past years to write down their experience. As soon as they come in, you will read them here in their own words, with name and situation. A handful of real stories beats a page full of polished words.
- 500+ mortgages guided
- 45+ lenders compared
- 17 years of experience
Want to share your experience? After completion you'll receive an invitation.
Not your moment yet? Set a reminder for your rate reset
Leave the end date of your fixed-rate period. I get in touch well in advance, so you can choose without rushing.
Frequently asked questions
The costs consist of penalty interest, notary fees (around 1,100 to 1,750 euros for the transfer and mortgage deeds), a valuation (around 750 euros) and advice fees. The penalty interest is often the largest item and depends on your remaining fixed-rate period and the difference in rates. I calculate the exact costs for you in a free orientation call.
A rule of thumb: when the rate difference is more than 0.5% and you still have at least 10 years to run, it is worth having it calculated. Treat that as a first guide only: I always work it out exactly, including every cost, and show you when you break even. Also when the answer is no.
Yes, though you will pay penalty interest to your current bank. Sometimes switching still works out better despite that penalty. I calculate the exact tipping point so you know whether it pays off.
Six to ten weeks on average. The main steps: the advisory conversation (two weeks), requesting the new offer from the bank (four weeks), then scheduling the valuation and the notary. I guide the whole process from start to finish.
No. When refinancing you keep your right to mortgage interest deduction. The conditions stay the same as with your original mortgage. I make sure everything transfers correctly for tax purposes.
One conversation. That's all it takes.
No obligations, no sales pitch. Just 30 minutes where I listen to your situation and tell you what's possible. After that, you decide.
No catch. Just a good conversation.
Prefer to call first? +31 6 22 13 14 29Free orientation call · 30 minutes · No obligations